Has Marketing Automation Moved Us Closer to Buyer-Centric Demand Generation?
The central idea behind this blog has always been buyer-centric demand generation: putting the buyer, not the campaign calendar, at the centre of marketing. In a world where buyers research online, read reviews and ask peers before speaking to a vendor, the content journey each buyer takes is personal. Mass, product-centric marketing works less well every year.
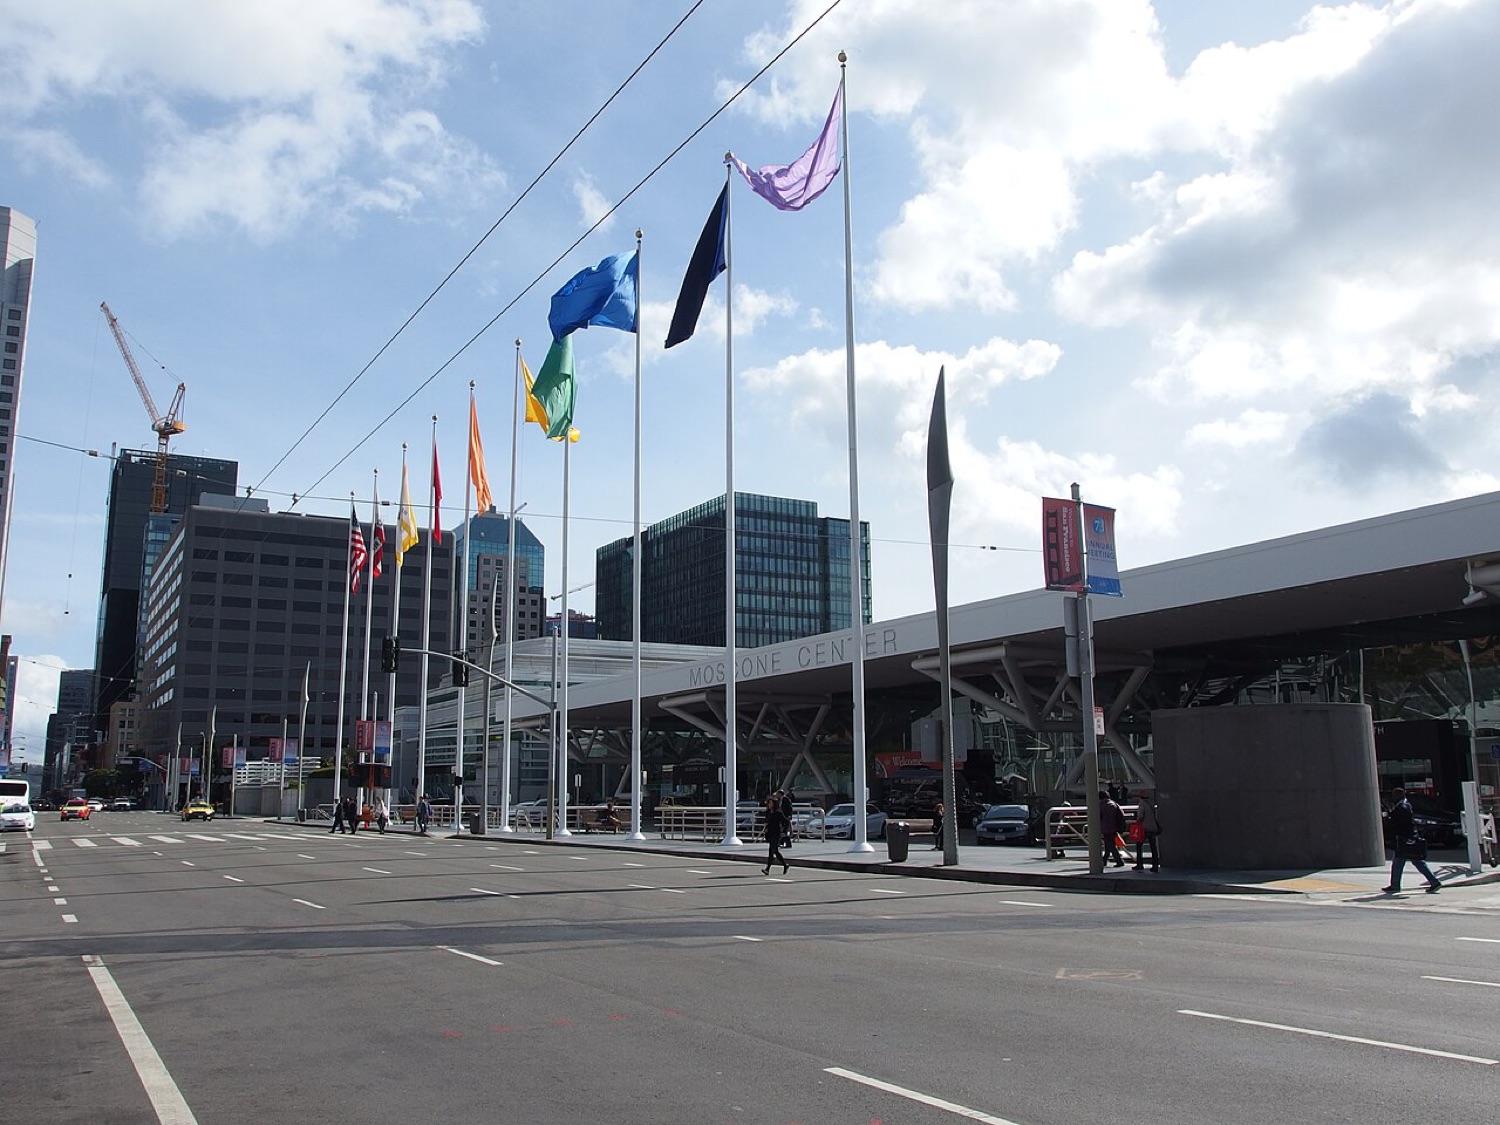
In September 2011 we came back from Dreamforce, Salesforce's annual conference at the Moscone Center in San Francisco, which reportedly drew around 45,000 people that year. The question we asked then still applies: does each new platform release actually help marketers become more buyer-centric?
What we saw in 2011
The big theme was the "social enterprise": storing social data in the customer database, creating employee social networks and tapping customer communities. It was a compelling vision for sales, service and collaboration. It said much less about marketing and demand generation. CRM and marketing automation were designed to make data collection, campaign execution and lead qualification more efficient, not necessarily to make them buyer-centric. Many teams that bought the technology carried on with batch-and-blast email, just faster.
What has changed by 2026
The market consolidated. Most of the independent vendors of 2011 now belong to larger suites: Eloqua to Oracle, Marketo to Adobe, Pardot to Salesforce (now sold as Marketing Cloud Account Engagement), while HubSpot grew from small-business inbound software into a full platform. Microsoft built journeys into Dynamics 365. Capabilities that were premium in 2011 (scoring, progressive profiling, multi-step nurturing, CRM sync) are now standard. The new frontier is intent data, account-level engagement, AI-generated content and predictive scoring.
| Platform type | Typical strengths | Watch out for |
|---|---|---|
| Enterprise B2B suites | Complex nurturing, deep CRM integration, governance, many business units | Cost, implementation time, need for specialist admins |
| All-in-one inbound platforms | Ease of use, content tools, built-in CRM, fast start | Price rises steeply with contacts and features |
| CRM-native marketing | One database with sales, simple reporting | Less flexible nurturing logic |
| Email-first SMB tools | Low cost, quick campaigns | Limited scoring and attribution |
| Vertical CRMs (e.g. iGaming) | Real-time triggers, player-level segmentation, gamification | Built for consumer volumes, not B2B buying groups |
We do not rank vendors here. Every platform on the list can run a good buyer-centric programme, and every one can run a bad one. The deciding factor is still the process: buying-process research, content mapped to stages, scoring, and the hand-off to sales. See program translation and documenting your processes.
Where automation really is buyer-triggered: betting and casino CRM
If you want to know what fully buyer-triggered marketing looks like, the clearest example is the iGaming industry. Online casinos and sportsbooks run CRM platforms built for their own needs, and names that come up often in the industry include Optimove, Fast Track and Xtremepush. They react to player behaviour in close to real time: a first deposit, an abandoned registration, a favourite team's upcoming match, a drop in activity. Messages are triggered by what the customer does, not by a calendar.
That is precisely the "bottom-up" demand generation we argued for in 2011, operating at consumer scale. B2B buying cycles are slower and decisions are made by groups, so the triggers are different, but the principle carries over. We explain the mechanics in marketing automation for betting operators.
So, are we closer?
Yes, technically. The tools to be buyer-centric are now cheap and widely available. Organisationally, less so. Many teams still measure sends, opens and MQL volume instead of buyer progress and revenue. Platforms have moved the bar; it is up to marketers to clear it.
Related reading